
On this page
ToggleOverview
Fraud isn’t just an unexpected financial hit; it’s a silent drain on your company’s resources, reputation, and long-term prospects. Beyond the immediate costs of fraud and deceitful schemes, businesses often shoulder hidden costs that ripple through operations, erode customer trust, and sap employee morale. These less obvious impacts can quietly undermine growth goals, distort decision-making, and inflate recovery costs long after the fraud itself is discovered. Understanding these concealed consequences is essential for any organization serious about resilience and sustained success.
In an era where threats constantly evolve and fraudsters refine their tactics, simply reacting after a loss is no longer enough. Leaders must appreciate how deeply fraud can affect every layer of a business, from brand perception to operational continuity, and build prevention strategies that are proactive, data-driven, and aligned with broader risk management goals. This article explores the full spectrum of fraud’s hidden costs and outlines practical ways to safeguard your organization before losses mount.
What is fraud?
Fraud is a deliberate act of deception intended to gain something of value, usually money, assets, or access, by misleading or manipulating others. It involves intentionally providing false information or concealing the truth to exploit a person, organization, or system. Fraud can occur in many forms, including financial scams, identity theft, data manipulation, or internal misconduct, and it poses serious legal, financial, and reputational risks to both individuals and businesses.
It is a pervasive challenge that can infiltrate any organization, leaving a trail of financial devastation in its wake. It’s an insidious threat that not only siphons off hard-earned profits but also undermines the integrity of your business. As you navigate the complexities of the business world, understanding the multifaceted nature and its repercussions is paramount.
The landscape of fraud is ever-evolving, with fraudsters continuously devising new schemes to exploit vulnerabilities within businesses. This dynamic nature necessitates a proactive and comprehensive approach to prevention. By understanding the specific threats that your business faces, you can tailor your prevention strategies to be both effective and resilient. The journey to safeguarding your business begins with a thorough appreciation of the hidden costs associated with it.

Tired of manual risk assessments that leave your board exposed?
Automate IT risk quantification with TrustCloud and confidently minimize CISO and Board liability.
Learn MoreUnderstanding the hidden costs
While the immediate financial losses due to fraud are evident, the hidden costs can be far more detrimental to the long-term health of your business. These costs manifest in various forms, including damage to your company’s reputation, loss of customer trust, and erosion of employee morale. The reputational damage inflicted by it can deter potential clients and partners, leading to lost opportunities and revenue. Furthermore, the breach of trust can have a cascading effect, undermining the confidence that customers and employees have in your organization.
Another significant hidden cost is the expenditure associated with investigating it, implementing remedial actions, and possibly facing legal proceedings. These activities not only drain financial resources but also divert attention and energy away from your core business operations. Additionally, the psychological impact on you and your team can be profound, with the stress and anxiety associated with handling it potentially affecting decision-making and overall well-being.
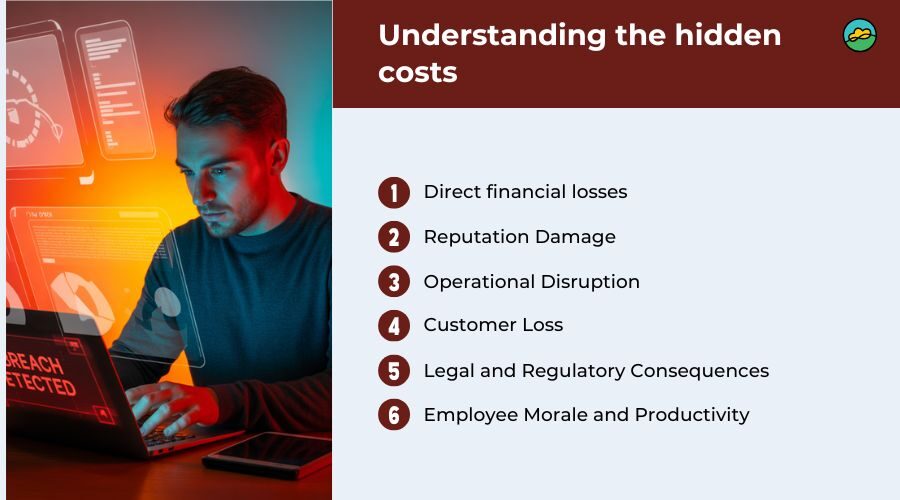
Understanding these hidden costs underscores the importance of preemptive measures in fraud prevention. By recognizing the far-reaching consequences of it, you can better appreciate the value of investing in comprehensive fraud prevention strategies.
- Direct financial losses
- Definition: Direct financial losses are the immediate monetary damages incurred due to fraudulent activities, including stolen funds and assets.
- Hidden Aspect: The hidden cost lies in the ripple effect on business operations, productivity, and long-term financial stability.
- Reputation Damage
- Definition: Reputation damage refers to the harm caused to a business’s public image and trustworthiness.
- Hidden Aspect: Rebuilding a tarnished reputation is a prolonged and resource-intensive process, impacting customer loyalty and brand value.
- Operational Disruption
- Definition: Operational disruption involves the disturbance of regular business activities due to investigations, recovery efforts, and system overhauls.
- Hidden Aspect: The indirect costs of interrupted operations can extend beyond immediate financial losses, affecting employee morale and client relationships.
- Customer Loss
- Definition: Customer loss refers to the departure of clients or customers who lose trust in a business due to fraudulent incidents.
- Hidden Aspect: The cost of acquiring new customers to replace those lost is often underestimated, along with the potential decline in customer lifetime value.
- Legal and Regulatory Consequences
- Definition: Legal and regulatory consequences involve fines, penalties, and legal actions resulting from fraud-related activities.
- Hidden Aspect: The impact on the organization’s compliance standing and the cost of legal proceedings can extend far beyond the immediate financial penalties.
- Employee Morale and Productivity
- Definition: Employee morale and productivity encompass the negative effects on staff motivation and efficiency stemming from the aftermath of fraud.
- Hidden Aspect: Low morale and decreased productivity may lead to increased turnover rates and recruitment costs.
Types of fraud that businesses commonly face
Businesses are susceptible to various types of fraud, each with its own set of challenges and implications. Common forms include asset misappropriation, where employees or outsiders steal or misuse the organization’s resources. This can range from skimming cash to misappropriating inventory or other assets. Another prevalent form is corruption, involving unethical practices such as bribery, kickbacks, and conflicts of interest, often undermining fair business practices and leading to significant financial and reputational damage.
Cyber fraud has emerged as a growing threat, with sophisticated attacks such as phishing, ransomware, and hacking exposing sensitive information and financial data. These cybercrimes not only result in direct financial losses but can also compromise customer data, leading to a breach of trust and potential legal ramifications. Additionally, financial statement fraud, though less common, can have catastrophic effects, involving the manipulation of financial records to present a misleading picture of a company’s financial health, potentially deceiving investors, regulators, and other stakeholders.
Being aware of these types is crucial in developing targeted prevention strategies. By identifying the specific threats your business faces, you can allocate resources more effectively to mitigate these risks.
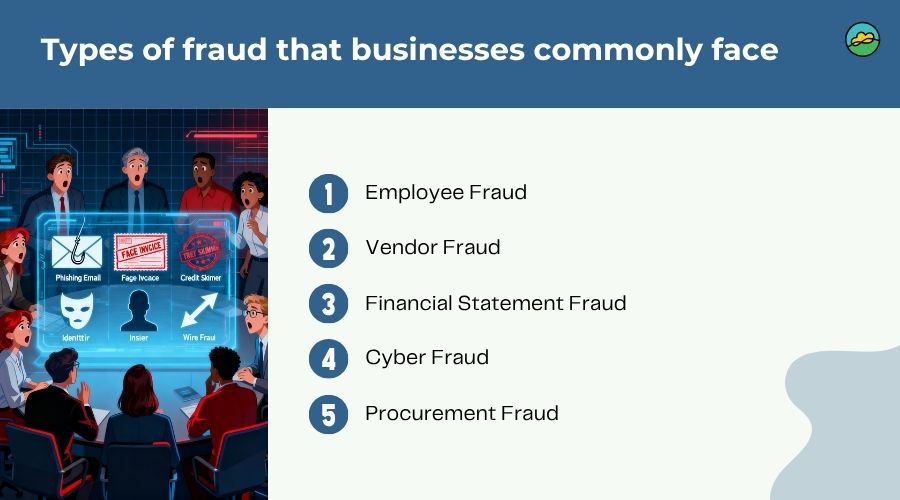
Businesses commonly face various types of fraud that can significantly impact their operations, financial health, and reputation. Here are five common types of fraud:
- Employee Fraud
Types:- Embezzlement: Misappropriation of funds or property by an employee.
- Expense Fraud: Employees submitting false expense claims for reimbursement.
- Payroll Fraud: Manipulating the payroll system to receive unearned compensation, such as falsifying timesheets or creating ghost employees.
- Vendor Fraud
Types:- Overbilling: Vendors charging more than agreed upon or for goods and services not provided.
- Kickbacks: Vendors offering bribes or incentives to employees in exchange for favourable treatment or contracts.
- Collusion: Vendors colluding with employees to defraud the company, such as inflating invoices and sharing the excess profits.
- Financial Statement Fraud
Types:- Revenue Manipulation: Falsifying sales figures to appear more profitable, often through premature revenue recognition or fictitious sales.
- Expense Manipulation: Underreporting expenses to artificially inflate profits, such as capitalizing expenses that should be expensed.
- Asset Misrepresentation: Overstating assets’ values or hiding liabilities to present a healthier financial position.
- Cyber Fraud
Types:- Phishing Attacks: Fraudulent attempts to obtain sensitive information by pretending to be a trustworthy entity in electronic communications.
- Malware and Ransomware: Infiltrating systems to steal data or lock files, demanding payment for their release.
- Data Breaches: Unauthorized access to confidential business information, often resulting in data theft and identity fraud.
- Procurement Fraud
Types:- Bid Rigging: Manipulating the bidding process to favour a particular vendor, often through collusion between employees and suppliers.
- False Invoicing: Creating fake invoices for goods or services not received, often in collusion with vendors.
- Product Substitution: Supplying inferior products while charging for higher-quality goods, often undetected until significant losses occur.
Each of these fraud types poses unique challenges and requires specific detection and prevention strategies to safeguard the business from potential financial and reputational damage.
Read our Building Cyber Resilience: Strengthening Your Defense Against Online Threats article to learn more about cyber resilience.
The financial impact of fraud on businesses
The financial repercussions of fraud extend beyond the direct losses incurred. These incidents can lead to a domino effect, impacting various facets of your business. For instance, the discovery of significant fraud can lead to a loss of investor confidence, resulting in a drop in stock prices for publicly traded companies or a withdrawal of investment in privately held firms. The costs associated with rectifying the it, such as legal fees, fines, and the expense of implementing new controls, can also strain your financial resources.
Moreover, the indirect costs, such as increased insurance premiums, higher borrowing costs due to a damaged credit rating, and the potential loss of business licenses or certifications, can further exacerbate the financial strain on your organization. These factors highlight the imperative need for a proactive approach to prevention, emphasizing the adage that an ounce of prevention is worth a pound of cure.
Case studies: real-life examples of businesses affected by fraud
Examining real-life instances of businesses impacted by fraud provides valuable insights into the diverse nature of fraud and its consequences. One notable example is the case of Enron Corporation, which collapsed due to widespread corporate fraud and corruption. This scandal not only led to significant financial losses for investors but also resulted in a loss of trust in corporate America, prompting the introduction of stricter regulatory measures.
Another example involves a small business that fell victim to embezzlement by a trusted employee. The employee siphoned off funds over several years, leading to a financial crisis that nearly bankrupted the company. This case underscores the importance of internal controls and the need for vigilance at all levels of an organization.
These examples illustrate the critical need for businesses to remain vigilant against fraud. By learning from the experiences of others, you can bolster your defenses and prevent your organization from becoming a similar cautionary tale.
Identifying and preventing fraud in your organization
The first step in preventing fraud is to recognize the warning signs. Unusual financial transactions, discrepancies in records, and changes in employee behavior can all be indicators of fraudulent activity. Implementing strong internal controls, such as segregation of duties, regular audits, and transparent financial reporting, can significantly mitigate the risk of fraud.
Cultivating a culture of integrity and transparency within your organization is equally important. Encouraging employees to report suspicious activity without fear of retaliation can help uncover it at early stages. Additionally, conducting thorough background checks during the hiring process can prevent potential fraudsters from joining your organization.
By taking these proactive measures, you can create a robust framework for preventing fraud, safeguarding your organization’s assets, and ensuring its long-term success.
Prove how your security program protects your business and drives growth
Showcase financial liability reduction with IT risk quantification, cut costs while automating 100s of manual security and GRC workflows, and accelerate revenue by earning regulator, auditor and customer trust.
Strategies for fraud prevention
The specter of fraud looms larger than ever, casting a shadow over businesses and individuals alike. With cunning fraudsters constantly evolving their tactics, staying one step ahead is not just advisable; it’s imperative. This article unveils an arsenal of strategies for fraud prevention, designed to fortify your defenses and safeguard your assets against the ever-growing threat.
From cutting-edge technology to time-tested methods, our comprehensive guide offers invaluable insights and practical steps that can be seamlessly integrated into your security framework. Whether you’re a seasoned professional seeking to tighten your operation’s security or an individual aiming to protect your personal information, these strategies promise a fortress of security in an unpredictable world.
- Implement robust internal controls
- Risk Assessment: Conduct regular risk assessments to identify vulnerabilities and implement internal controls tailored to the organization’s specific risks.
- Segregation of Duties: Enforce segregation of duties to minimize the risk of collusion and unauthorized activities.
- Employee Training and Awareness
- Education Programs: Implement comprehensive training programs to educate employees about fraud risks, prevention techniques, and reporting procedures.
- Whistleblower Hotlines: Establish anonymous whistleblower hotlines to encourage employees to report suspicious activities without fear of retaliation.
- Enhance cybersecurity measures
- Secure IT Infrastructure: Invest in robust cybersecurity measures to protect sensitive data and prevent unauthorized access.
- Regular Audits: Conduct regular cybersecurity audits to identify and address potential vulnerabilities.
- Due Diligence in Vendor Relationships
- Vendor Screening: Screen and vet vendors thoroughly to ensure their integrity and adherence to ethical business practices.
- Contractual Safeguards: Include contractual safeguards and penalties for non-compliance in vendor agreements.
- Monitoring and Analytics
- Transaction Monitoring: Implement real-time transaction monitoring systems to identify and flag unusual activities.
- Data Analytics: Utilize advanced data analytics tools to detect patterns indicative of fraudulent behavior.
- Fraud Risk Management Framework
- Comprehensive Framework: Develop and implement a comprehensive fraud risk management framework that aligns with the organization’s overall risk management strategy.
- Regular Reviews: Conduct regular reviews and updates to adapt to changing business environments and emerging fraud threats.
Implementing a strong prevention program
A comprehensive fraud prevention program is essential in protecting your organization from financial losses. This program should encompass a range of strategies, including risk assessment, internal controls, employee training, and incident response plans. Conducting regular risk assessments can help you identify and address vulnerabilities within your organization, while effective internal controls can prevent fraudulent activities from occurring.
Employee training is critical in raising awareness about the dangers of fraud and the role that each individual plays in preventing it. By educating your team on common fraud schemes and the importance of adhering to ethical practices, you can foster a culture of integrity. Additionally, having a clear incident response plan in place ensures that your organization is prepared to act swiftly and decisively in the event of fraud, minimizing financial and reputational damage.
Read the article “How data analytics detects fraud: Real-time techniques for today’s risks” to learn more
The role of technology in preventing
Advancements in technology have introduced powerful tools in the fight against it. Fraud detection software, utilizing artificial intelligence and machine learning, can analyze patterns and anomalies in data, flagging suspicious activities for further investigation. Implementing secure authentication methods, such as biometrics and two-factor authentication, can enhance the security of your financial transactions and data.
Moreover, blockchain technology offers a promising solution for increasing transparency and reducing the risk of fraud in transactions. By maintaining a secure and immutable ledger of transactions, blockchain can help prevent tampering and ensure the integrity of financial records.
Leveraging these technological solutions can significantly bolster your prevention efforts, providing an additional layer of security and peace of mind.
Training and educating employees on prevention
Employees are often the first line of defense against fraud. Providing comprehensive training on fraud prevention is crucial in equipping your team with the knowledge and skills needed to identify and prevent fraudulent activities. This training should cover the different types of fraud, the warning signs to watch for, and the procedures for reporting suspected fraud.
Creating a culture where employees feel empowered to speak up about unethical behavior is essential. Encouraging open communication and providing channels for anonymous reporting can help uncover it before causing any significant damage. Regularly updating training materials and conducting refresher courses can ensure that your team remains vigilant and informed about the latest prevention strategies.
Read the “Uncovering fraud with data analytics: 4 cutting-edge techniques to detect anomalies” article to learn more!
Working with law enforcement and legal resources
In the event of fraud, collaborating with law enforcement and legal resources is crucial in navigating the aftermath and pursuing justice. Reporting fraud to the appropriate authorities can help in the investigation and prosecution of the perpetrators. Additionally, seeking legal advice can guide you in recovering losses and protecting your organization from further harm.
Building relationships with law enforcement and legal professionals before an incident occurs can facilitate a more effective response. These partnerships can also provide valuable insights into preventing future incidents it, and enhancing your overall security posture.
The importance of regular audits and internal controls
Regular audits are a critical component of an effective prevention strategy. By providing an independent assessment of your organization’s financial records and internal controls, audits can identify weaknesses and recommend improvements. Implementing strong internal controls, such as separation of duties, access controls, and authorization procedures, can deter fraud and ensure the accuracy of financial reporting.
Continuously monitoring and updating your internal controls in response to changes in your business environment is essential. This proactive approach can help you stay ahead of potential threats and maintain a secure and trustworthy financial system.
Fraud prevention measures that are specific to different industries
Fraud prevention strategies should be tailored to the specific risks and challenges faced by your industry. For example, retailers may focus on preventing shoplifting and return fraud, while financial institutions may prioritize safeguarding against cyber fraud and identity theft. Understanding the unique vulnerabilities of your industry can help you develop targeted measures to protect your business.
Collaborating with industry associations and participating in forums can provide insights into best practices and emerging threats. By staying informed and adapting your strategies accordingly, you can effectively mitigate the risk of fraud and safeguard your organization’s future.
- Leadership Commitment
- Top-Down Approach: Leadership commitment to ethical practices sets the tone for the entire organization.
- Visible Participation: Leaders should actively participate in fraud prevention initiatives, reinforcing their commitment.
- Communication and Transparency
- Open Communication: Foster a culture of open communication where employees feel comfortable reporting concerns without fear of reprisal.
- Transparency in Policies: Clearly communicate fraud prevention policies and procedures to all stakeholders.
- Continuous Monitoring and Adaptation
- Adaptive Framework: Implement a continuous monitoring and adaptive framework that evolves with changing risks.
- Regular Training: Keep employees updated with regular training sessions on emerging trends and prevention techniques.
- Whistleblower Protection
- Anonymous Reporting: Ensure whistleblower protection by establishing anonymous reporting channels.
- Non-Retaliation Policy: Clearly communicate a non-retaliation policy to encourage employees to come forward without fear of consequences.
Read the “Powerful fraud prevention tactics for 2025: Detect and respond swiftly” article to learn more
Measuring the effectiveness of fraud prevention
- Incident Reduction
- Quantitative Analysis: Measure the reduction in the number and severity of incidents over time.
- Benchmarking: Compare incident rates with industry benchmarks to assess the organization’s relative performance.
- Employee Awareness and Reporting
- Surveys and Feedback: Conduct surveys and gather feedback to assess employee awareness of risks and reporting mechanisms.
- Increase in Reports: An increase in the number of reported concerns may indicate improved awareness.
- Customer Satisfaction and Trust
- Customer Feedback: Monitor customer satisfaction and collect feedback to gauge the level of trust in the organization.
- Retention Rates: Track customer retention rates to assess the impact of prevention on customer relationships.
Summing it up
The hidden costs of fraud extend beyond immediate financial losses, encompassing reputation damage, operational disruptions, and long-term impacts on employee morale and customer trust. To effectively prevent fraud and mitigate its hidden costs, organizations must adopt a holistic approach that combines robust internal controls, employee training, cybersecurity measures, and continuous monitoring. Building a culture of prevention, led by committed leadership and supported by transparent communication and adaptive frameworks, is crucial for safeguarding organizational assets and maintaining long-term resilience in the face of evolving threats.
This poses a significant threat to businesses, but with a comprehensive understanding and proactive approach, you can protect your organization from its financial and reputational damages. By recognizing the hidden costs of it, implementing strong prevention measures, leveraging technology, and fostering a culture of integrity, you can build a resilient defense against this pervasive threat.
Empowering your employees with the knowledge to detect and prevent it, regularly auditing your processes, and collaborating with legal and law enforcement professionals are critical components of a successful prevention strategy. Tailoring your efforts to the specific needs and challenges of your industry will further enhance your ability to safeguard your business.
Taking proactive steps to prevent it is not just a financial imperative; it’s a commitment to upholding the trust and confidence of your customers, employees, and stakeholders. By dedicating the necessary resources and attention to prevention, you can ensure the long-term success and integrity of your organization.
FAQs
What are the hidden costs of fraud?
While the immediate financial losses from fraud are evident, the hidden costs can be far more detrimental to a business’s long-term health. These costs can include:
- Reputation damage: Fraud can severely harm a business’s public image and trustworthiness, making it difficult to attract new customers and partners.
- Operational disruption: Investigations, recovery efforts, and system overhauls can disrupt normal business activities and impact productivity.
- Customer loss: Clients may lose trust in a business after a fraud incident and take their business elsewhere.
- Legal and regulatory consequences: Businesses may face fines, penalties, and legal action due to fraud-related activities.
- Employee morale and productivity: The aftermath of fraud can negatively affect staff motivation and efficiency, leading to increased turnover rates and recruitment costs.
What are the most common types of fraud businesses face?
Businesses are vulnerable to various types of fraud, including:
- Employee fraud: Embezzlement, expense fraud, and payroll fraud are common examples.
- Vendor fraud: This includes overbilling, kickbacks, and collusion between vendors and employees.
- Financial statement fraud: This involves manipulating financial records to misrepresent a company’s financial health.
- Cyber fraud: Phishing attacks, malware and ransomware, and data breaches are increasing threats in the digital age.
- Procurement fraud: Bid rigging, false invoicing, and product substitution are common schemes.
How can businesses identify and prevent fraud?
Preventing fraud starts with recognizing the warning signs. Unusual financial transactions, discrepancies in records, and changes in employee behavior can all indicate fraudulent activity. Here are some key steps:
- Implement robust internal controls: Regular risk assessments, segregation of duties, and transparent financial reporting can mitigate fraud risks.
- Cultivate a culture of integrity: Encourage employees to report suspicious activity without fear of retaliation.
- Conduct thorough background checks: Screen potential employees to prevent hiring individuals with a history of fraudulent behavior.
What is the role of technology in fraud prevention?
Technology plays a crucial role in modern fraud prevention. Tools like fraud detection software, powered by AI and machine learning, can analyze data to identify suspicious activity. Other technological solutions include:
- Secure authentication methods: Biometrics and two-factor authentication enhance the security of financial transactions and data.
- Blockchain technology: Blockchain can increase transparency and reduce fraud risk by maintaining secure and tamper-proof transaction records.
How can employees be trained to prevent fraud?
Employees are the first line of defense against fraud. Comprehensive training is essential to equip them with the knowledge and skills to identify and prevent it. Training should cover:
- Types of fraud: Employees need to understand the various schemes used by fraudsters.
- Warning signs: They should be trained to recognize red flags and suspicious activity.
- Reporting procedures: Employees need to know how to report suspected fraud safely and confidentially.
What is the importance of regular audits and internal controls?
Regular audits are vital for effective fraud prevention. They provide independent assessments of financial records and internal controls, identifying weaknesses and recommending improvements. Strong internal controls, such as:
- Separation of duties: Different individuals should be responsible for different parts of a transaction process.
- Access controls: Restrict access to sensitive data and systems based on job roles and responsibilities.
- Authorization procedures: Require approval for transactions above certain thresholds.